
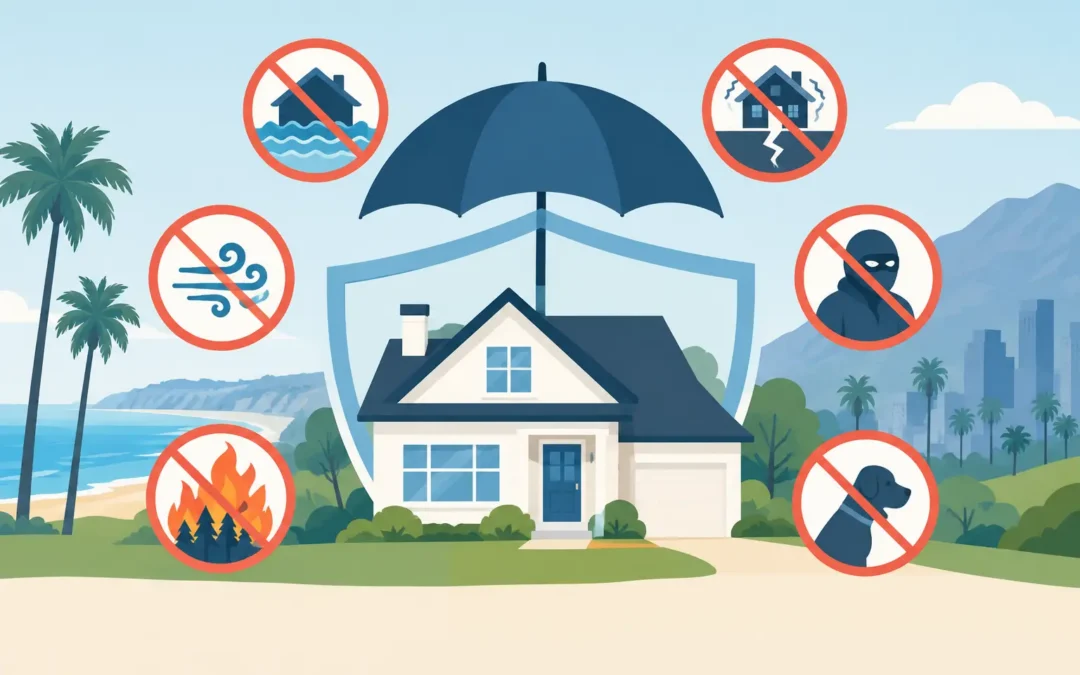
A home insurance policy can look reassuring right up until a claim reveals what it does not pay for. The top home insurance exclusions are especially important for homeowners in Central and Northern California, where wildfire exposure, rural infrastructure, steep terrain, and older homes can create expensive gaps. A lower premium is not a bargain if the coverage leaves you responsible for rebuilding costs, temporary housing, or a major liability claim.
The policy jacket is not the whole story. Exclusions, endorsements, deductibles, limits, and conditions all work together to determine what happens after a loss. Here are the areas worth reviewing before you need to file a claim.
Top Home Insurance Exclusions That Create Costly Gaps
Flood damage
Standard homeowners insurance generally does not cover flood damage. This catches many homeowners off guard because they assume water damage is water damage. It is not. If water enters your home after a creek overflows, a hillside gives way during heavy rain, or storm runoff flows across the ground and into the structure, the claim may be considered flood-related.
A home does not need to sit next to a river to have flood exposure. Burn scars, sloped lots, clogged culverts, seasonal drainage paths, and intense winter storms can all change the risk. Separate flood coverage may be worth considering, particularly if your property has a downhill driveway, basement, crawl space, or history of runoff.
Earthquake and earth movement
California homeowners policies typically exclude earthquake damage. The exclusion often extends beyond a major seismic event to earth movement such as settling, landslides, mudflow, and subsidence. The details matter because a hillside property may face movement-related risks even if it is not near an obvious fault line.
Earthquake insurance is generally purchased separately and usually comes with a significant deductible. That trade-off deserves a clear conversation. Some homeowners choose the deductible because rebuilding a damaged home without any earthquake coverage would be far more difficult. Others decide the cost does not fit their situation. The key is making that decision knowingly, not discovering the exclusion after structural damage occurs.
Wear, tear, and deferred maintenance
Insurance is designed for sudden, accidental losses, not the cost of owning and maintaining a home. Roof deterioration, dry rot, corroded plumbing, pest damage, foundation settling, and gradual leaks are common exclusions or claim denials.
For foothill and mountain properties, maintenance documentation can be particularly valuable. Keep records for roof replacement, tree work, chimney inspections, drainage repairs, and plumbing updates. Those records cannot turn a maintenance issue into a covered claim, but they can help show that a loss was sudden rather than the result of a long-running problem.
Water damage with a slow cause
A burst supply line may be covered. A leak that has been dripping behind a wall for months may not be. Policies often distinguish between sudden and accidental discharge of water and seepage or leakage that occurs over time.
Water backup is another separate concern. Damage caused when a sewer or drain backs up is frequently excluded unless the policy includes a water backup endorsement. This coverage is often affordable compared with the cost of cleaning up contaminated water, replacing flooring, and repairing walls. It is worth checking even for homes on septic systems, where a backup can still create a serious loss.
Ordinance or law costs
After a covered fire, your insurer may pay to restore the damaged portion of the home. But local building codes may require upgrades that did not exist when the house was built. That can include electrical improvements, fire-resistant materials, accessibility changes, foundation work, or updated energy requirements.
Coverage for ordinance or law can help with those added costs, but it is often limited. This is a major issue for older homes in wildfire-prone communities, where the cost to rebuild may involve code updates and stricter defensible-space requirements. Ask how much ordinance or law coverage is included and whether it reflects the age, location, and construction of your home.
Wildfire-related limits, deductibles, and conditions
Fire is usually a covered peril under a standard homeowners policy, but wildfire protection is more complicated than simply checking whether fire appears on the declarations page. In high-risk California areas, insurers may apply special deductibles, impose brush-clearance conditions, require roof or vegetation improvements, or decline to renew based on changing wildfire models.
A policy can also have a dwelling limit that is too low for a post-fire rebuild. Construction labor, debris removal, permit costs, access challenges, and the demand surge after a regional fire can push rebuilding costs well beyond an old estimate. Extended replacement cost coverage, guaranteed replacement features where available, and adequate debris-removal limits should be reviewed carefully.
The California FAIR Plan can provide an important fire insurance option when standard coverage is unavailable, but it may not provide the complete protection most homeowners expect. It can leave gaps for liability, water damage, theft, loss of use, and other exposures unless paired with a separate companion policy. The right structure depends on the property and the policy terms, not simply on whether a home has fire coverage.
Other Exclusions Homeowners Should Not Overlook
Some exclusions do not make headlines, but they can affect everyday risks. Review whether your policy limits or excludes:
- Home-based business property, business equipment, or liability from clients visiting your home
- Short-term rental activity, including occasional rental of a second home or guest unit
- Certain dog breeds, animal-related injuries, or livestock kept on rural property
- Vacant-home losses, especially if a second home sits unoccupied for an extended period
- Mold remediation beyond a small stated limit, even when mold follows a covered water loss
- Losses tied to power failure away from your property, such as spoiled food or failed systems
These are not always absolute exclusions. Coverage can vary by insurer, endorsement, occupancy type, and the facts of a claim. A detached workshop used for a hobby may be treated differently from a workshop where a business operates. A guest cabin used by family may be insured differently than one listed for rent online.
Liability Coverage Can Have Its Own Gaps
Homeowners often focus on the house itself and overlook personal liability coverage. Liability coverage can help if someone is injured on your property or if you accidentally damage someone else’s property. However, it may exclude business activities, intentional acts, certain vehicles, and some animal-related claims.
For rural properties, liability questions can extend to gates, private roads, swimming pools, ATVs, livestock, and visitors walking uneven terrain. An umbrella policy may add an extra layer of liability protection, but it also has requirements. Your underlying homeowners and auto liability limits may need to meet certain levels before umbrella coverage applies.
How to Review Your Policy Before a Loss
Start with your declarations page, but do not stop there. Confirm the dwelling limit, other structures limit, personal property limit, loss-of-use amount, liability limit, deductibles, and every endorsement. Then ask for the full policy form and exclusions. The declarations page tells you what you bought; the policy language explains how it responds.
Pay close attention to replacement cost. Market value, tax assessment, and what you paid for the home are not reliable rebuilding estimates. A home in a remote area may cost more to rebuild because crews, materials, and equipment must travel farther, while narrow roads or steep lots can complicate construction after a fire.
Finally, disclose how the property is actually used. Tell your broker if it is a vacation home, rented periodically, has a guest unit, includes a shop, or is vacant for part of the year. A policy built on incomplete information can create trouble when you need it most.
Foothill Fire Insurance helps homeowners compare available options with a clear view of coverage, deductibles, and potential gaps. Before the next renewal or purchase closing, gather your current declarations page, prior inspection reports, and basic details about the home. A careful review now gives you more choices than a rushed search after a non-renewal, wildfire warning, or loss.